Market stochastic expert system strategy
Market stochastic expert system strategy is defined by the local calculation documented below.
This entry has an incomplete verified explanation or executable case and is excluded from search indexing. Known definitions and missing inputs are distinguished below.
Purpose and construction
Market stochastic expert system strategy is defined by the local calculation documented below.
Market stochastic expert system strategy is applied to the chart series using the local definition below. Each period counts one bar on the active chart. The same period therefore covers a different amount of time on daily and intraday charts.
How to read it
Follow the intermediate calculations and final output definitions. Where external inputs are required, missing data is not a zero reading.
Strategy markers are formula conditions, not executed orders. Performance evaluation additionally requires explicit execution timing, transaction costs and position rules; markers alone do not establish returns.
Parameters
| Parameter | Default |
|---|---|
N1 | 18 |
N2 | 12 |
Parameter names match the variables in the calculation. After changing a lookback or smoothing period, recalculate on the same data to compare response speed. Defaults from another platform may not match this definition.
Original illustrated case
This original daily-bar case moves through an advance, a pullback and a wider-range recovery. It does not represent a real security. Where available, outputs are calculated by the project’s formula engine using the defaults above.
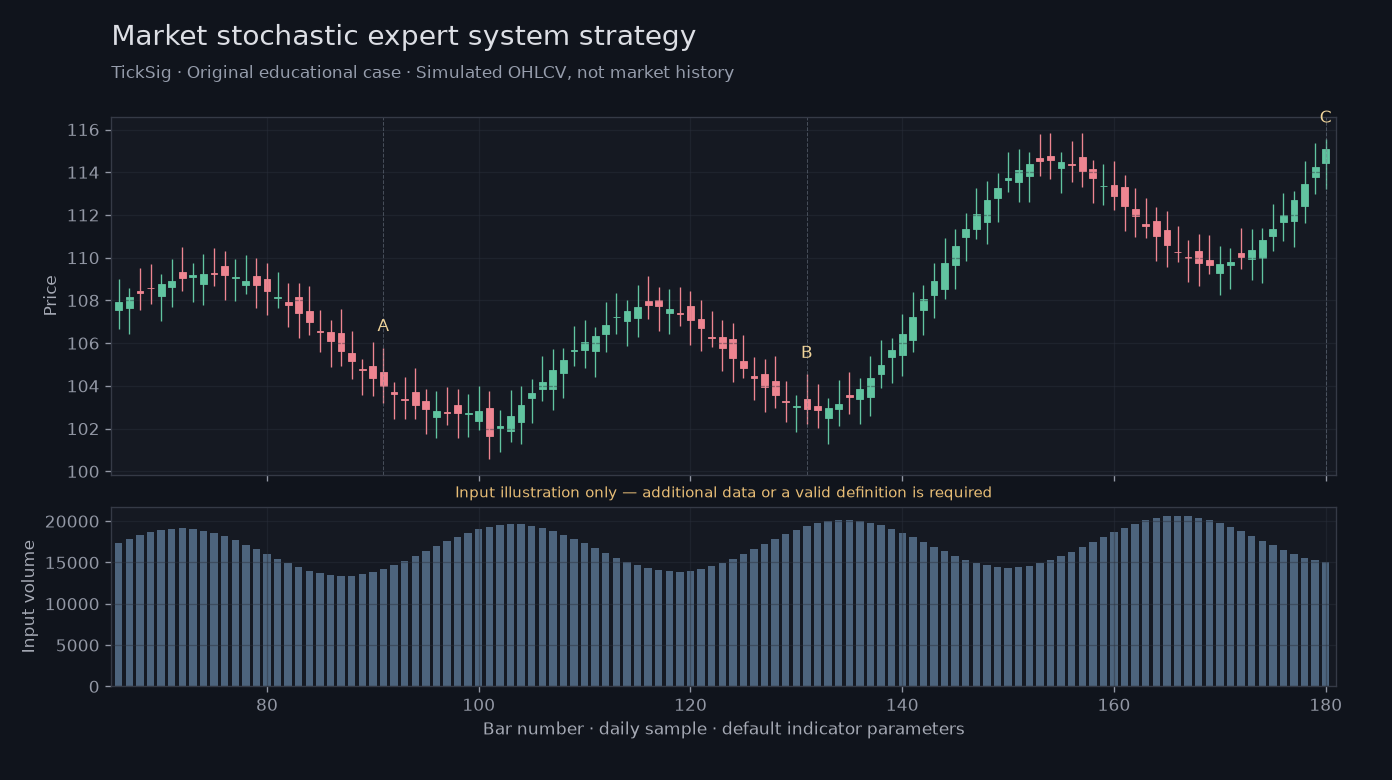
This sample cannot supply every required input, or the current definition needs verification. The table therefore retains input observations; complete the dependencies before comparing indicator results.
| Point | Bar | Close | Volume | Calculated outputs |
|---|---|---|---|---|
| A | 91 | 103.9764 | 14187 | — |
| B | 131 | 102.9084 | 19368 | — |
| C | 180 | 115.09 | 15024 | — |
To reproduce: retain the same OHLCV series and default settings, then compare outputs bar by bar. Warm-up bars can have no value. The case-generation script and local definition are stored with the project, so plotted curves are calculated rather than hand-drawn.
Local calculation
The local definition is shown below. Display labels can be translated; the case calculation uses original source identifiers. A shared indicator name does not guarantee identical calculations across platforms.
RSV:=(INDEXC-LLV(INDEXL,N1))/(HHV(INDEXH,N1)-LLV(INDEXL,N1))*100;
K:=SMA(RSV,N2,1);
HSL:VOL/100/(FINANCE(7));
ENTERLONG: CROSS(K,20);
EXITLONG: (CROSS(HSL,5) OR CROSS(K,80));
Limitations
- Follow the intermediate calculations and final output definitions. Where external inputs are required, missing data is not a zero reading.
- Timeframe, adjustments, warm-up length and data units affect results. Align these before comparing charts.
- This definition requires inputs beyond OHLCV, such as benchmark, share-count or cost data. Do not infer a result when these inputs are incomplete.
Questions
Why can Market stochastic expert system strategy differ across platforms?
Compare inputs, default periods, smoothing, offsets and data units before comparing the final value. This guide uses the local source definition rather than assuming that an external example has the same settings.
Does the example show a real trade?
No. The figure and table use simulated data to explain calculations and chart reading. They contain no real orders and make no return or win-rate claim.
References
The calculation comes from the project’s indicator registry. Primary references below provide related conceptual reading. Figures and numerical cases are independently produced for this project.